


AutoRek’s Jeff McGee explains why the central clearing mandate for U.S. Treasurys will create new reconciliation, margining, and settlement woes.
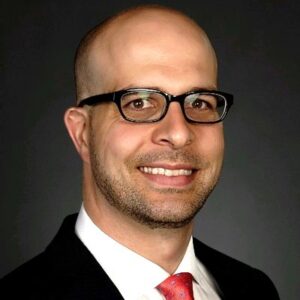
Jeff McGee, product & solutions manager at AutoRek
The U.S. Treasury market is about to go through one of the largest structural transformations in decades.
Under the US Securities and Exchange Commission (SEC) central clearing rules, a massive influx of cash and repo market transactions must migrate to central counterparties (CCPs) such as the Fixed Income Clearing Corp. (FICC), ICE Clear Credit, and CME Securities Clearing.
While compliance dates extend to December 31, 2026, for cash trades and June 30, 2027, for repos, waiting to adjust operational workflows is a recipe for post-trade paralysis.
Most market discussions focus on execution, margin requirements, and types of clearing models. However, the real operational strain will occur in the back and middle offices. Central clearing drastically increases the number of data touchpoints. This creates fragmented trading positions, settlement statuses, and collateral movements across multiple clearing houses, dealers, custodians, and internal ledger systems.
Despite being viewed as a compliance initiative, the reality is that it is an operational event that will prove to be transformative. The organizations that succeed will not simply connect to a CCP. They will build an automated and scalable control framework capable of reconciling every aspect of the new Treasury ecosystem.
The New Operational Reality
Historically, the majority of U.S. Treasury repo and cash trades settled bilaterally. Reconciliation was rather straightforward: internal books were matched against a single bilateral counterparty or custodian statement daily.
The introduction of central clearing shatters this simple framework. The move to a centrally cleared environment will require firms to rethink how they monitor, validate, and control trades, positions, cash, collateral, and accounting records. Not only does the number of sources that need to be reconciled increase, but the drivers of the underlying breaks also change.
1. Trade Lifecycle Reconciliation
Clearing introduces multiple new stages to the trade lifecycle that must be monitored and controlled.
- Trade execution, trade submission to CCPs, trade acceptance/rejection, novations, margin allocation, settlements.
Operations teams must now reconcile the entire lifecycle and not just the settlement outcome.
2. Segregation of Assets and Dynamic Margin Reconciliation
To protect client assets, the SEC mandate requires CCPs and direct participants to strictly segregate client margin from proprietary clearing house positions. This will require additional margin reconciliations:
- Gross Client Margin Reconciliation: Ensure client-level calculations match the clearing broker’s margin calls.
- Intraday Margin Calls: CCPs have the right to issue variation margin calls intraday. Back office teams will need the ability to reconcile margin calculations throughout the day and not just at the end of the day.
- Excess Collateral and Substitution Tracking: Middle and back office teams need to monitor collateral movements, haircuts, and tri-party locations across multiple pools to avoid costly over-collateralizations.
3. Repos Will Operationally Face Greater Complexity
The impact of central clearing may affect repo operations the most. The added complexity in some ways may become similar to cleared over-the-counter (OTC) derivatives.
- Repo desks will now have to reconcile:
- Principal balances
- Collateral positions, haircuts, substitutions, CCP margin activity
- Repo terminations
4. Netting Discrepancies & Trade Break Resolution
Central clearing relies on multilateral netting to optimize asset usage. Although netting reduces the gross settlement obligation, it adds a major complexity to reconciliation: gross-to-net translation and many-to-one matching.
- Your internal system may record 20 individual gross Treasury trades. The CCPs may report a single net cash and security settlement. If one leg fails or mismatches, the entire block settlement can break, and identifying the root cause requires granular matching capabilities that many infrastructures can’t handle.
The Cost of Unpreparedness: Fail Fees, Capital Charges and Operational Risks
The question isn’t whether firms can make the change to central clearing. They will because they must. The question is, at what cost will they make this transition?
In the U.S. Treasury Market, trade breaks are not just administrative headaches; they have immediate financial consequences:
- TMPG Fail Charges: Failed Treasury deliveries incur mandatory Treasury Market Practices Group (TMPG) penalty fees.
- Liquidity and Drag: Unmatched cash legs or delayed collateral returns drain cash reserves and can require overnight borrowing.
- Operational Bottlenecks: Staff spend increased time manually chasing trade breaks over emails, and spreadsheet-based infrastructures may not be able to handle the more complex workflows and increased volumes in an efficient way.
Turning Regulatory Requirements into an Advantage
Many firms will struggle with manual workarounds and throw more bodies at a manual process to stay afloat while raising costs. The market leaders will use this as an opportunity to modernize their infrastructure.
Automating reconciliation infrastructure and workflows now is about more than just complying with a new regulatory framework. It unlocks lower operational costs, collateral optimization, the ability to scale trade volumes, and lets your people focus on other meaningful work.
Is your company featured in this article? Contact us about reprints or licensing.
Leave a Reply